+86 13392271119
sales@eprochina.com

News
- News
- Product


Editor's note: this article is compiled from third-party industry sources. Product claims quoted herein are those of the brands mentioned and do not represent EPRO's own statements.
【行业动态】This article is compiled from Market Lens IQ (report updated August 22, 2026; 200 pages, base year 2025). Original link: https://www.marketlensiq.com/reports/air-fryer-market-10018

Data source: Market research report referenced in article
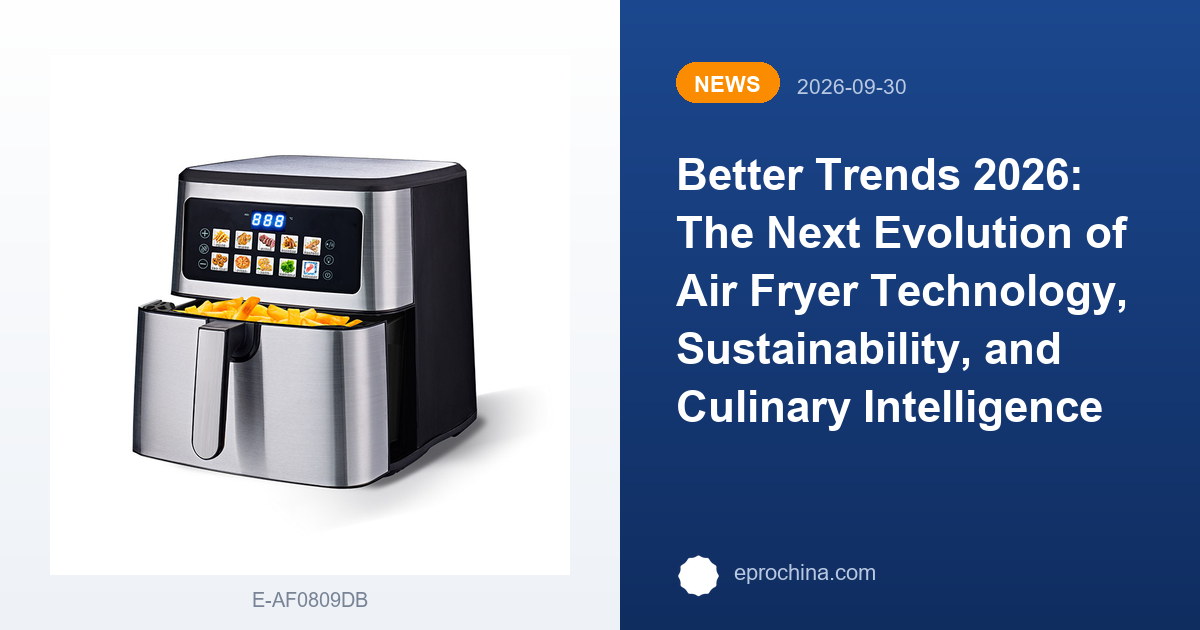
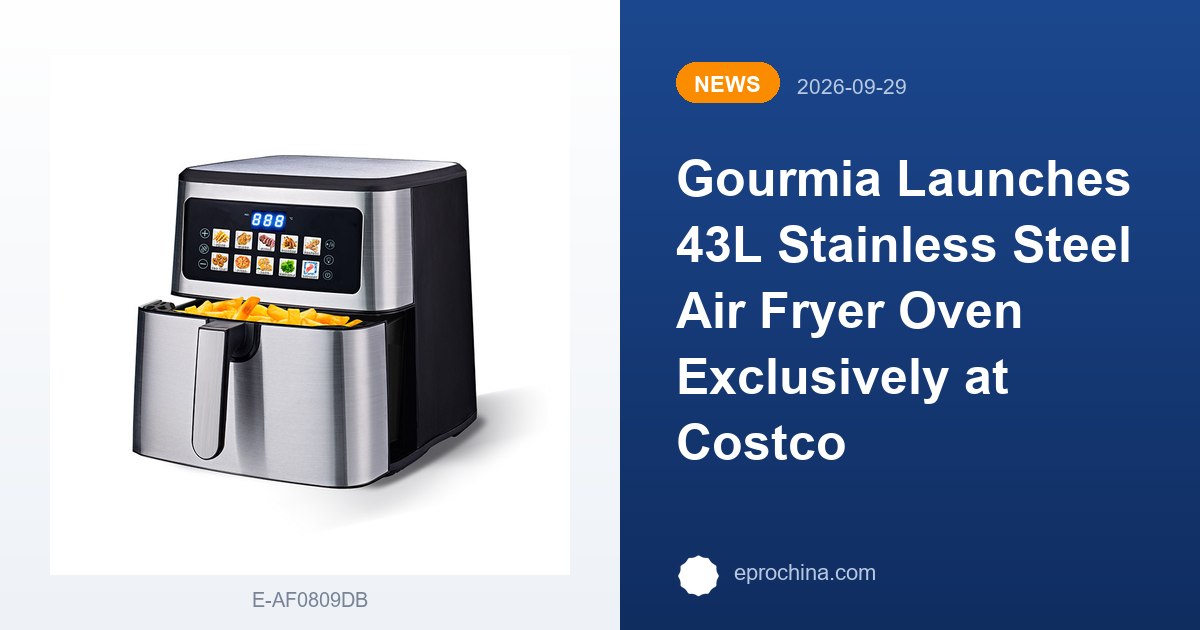
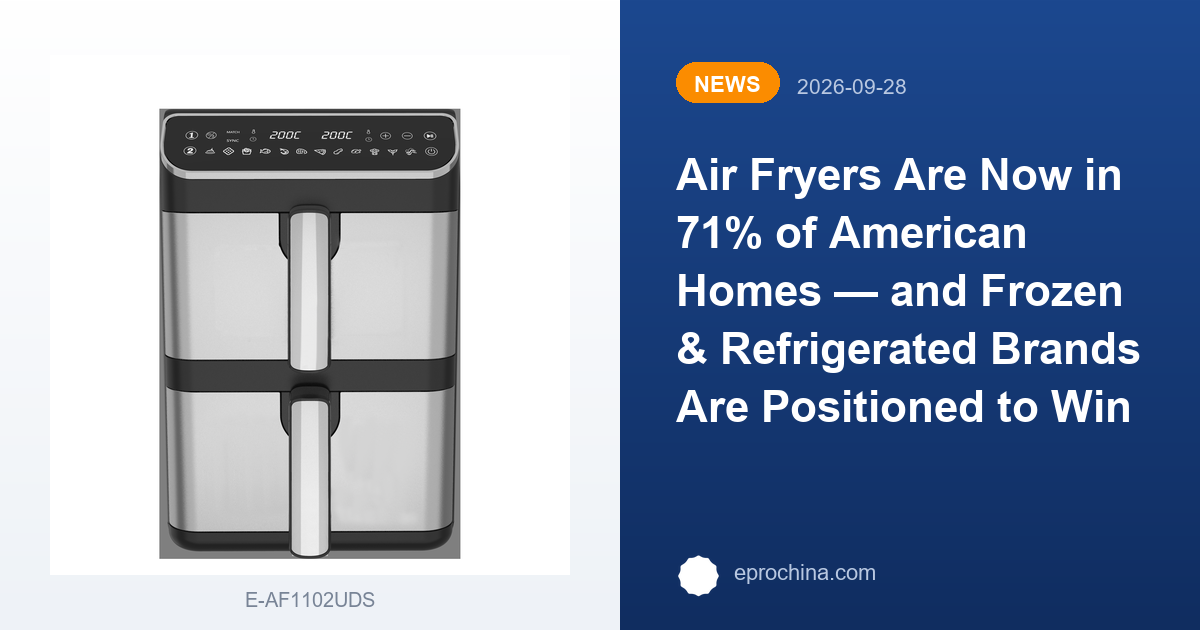
The global air fryer market reached USD 1.21 billion in 2025 and is projected to expand at a CAGR of 6.5% through the end of the decade and beyond, reaching approximately USD 2.00 billion by 2033, according to the latest report from Market Lens IQ. Residential demand remains the dominant revenue engine, accounting for more than three quarters of global air fryer revenue, supported by fast consumer adoption among single-person and small-family households. Manufacturers are responding with compact models, dual-zone cooking and app-enabled controls that lower the entry barrier for first-time buyers, while commercial applications are emerging in fast-casual restaurants and food trucks. The electric air fryer segment is capturing the bulk of this growth as household adoption accelerates across developed markets and tier-1 cities in Asia.
| Metric | Starting Point | Target / Current | Trend |
|---|---|---|---|
| Market Size | $1.21B (2025) | $2B (2033) | ↑ Growth |
| CAGR (Annual Growth) | - | 6.5% | ↑ Strong |
| Forecast Period | 2025 | 2033 | - |
| Key Product Trends | - | Smart/AI, Dual-Zone | ↑ Emerging |
On the competitive landscape, Newell Brands leads the market with a 28.2% company revenue share, followed by GoWISE USA at 20.3%, Wonderchef at 17.7% and Philips at 9.7%. Online marketplaces, especially Amazon and regional digital platforms, are redefining shelf space and enabling direct-to-consumer margin capture. Looking at regional dynamics, replacement cycles are shortening across mature markets as consumers upgrade to larger-capacity models, while European energy-efficiency labeling is forcing brands to redesign heating elements and insulation — creating both compliance pressure and differentiation opportunities for exporters.
For OEM and ODM buyers, the supply-chain picture in this report is equally significant. Component clusters for heating coils, thermostats and non-stick coatings remain concentrated in Guangdong province, keeping unit costs low — but trade tariffs and shipping volatility are pushing several global brands to dual-source production in India and Thailand. The strategic implication for vendors is clear: investment in connected product ecosystems and channel-specific pricing will separate share winners from followers over the 2025-2033 forecast window, and suppliers able to offer dual-zone, large-capacity and energy-efficient platforms will be best positioned to capture the upgrade wave.
Keep paying attention to EPRO for more latest news about air fryer.


Privacy Policy | Terms of Service

 English


